

Blogs
Global Customized Jewelry Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
The revenue for the global customized jewelry market has shown robust growth, with figures progressing steadily from 2020 through 2025 and beyond. In 2025, the market size is projected at 17,800 million, driven by digital customization tools and regional market expansion. Projections estimate a CAGR of 8.2% through 2035, reaching approximately 39,200 million by the end of the forecast period. This steady upward trajectory illustrates the ongoing transformation of consumer buying behavior, technological advancements, and entry of new market players.
Read More - https://bussinessinsights.com/research-report/global-customized-jewelry
By application, weddings and engagements together account for the majority of customized jewelry purchases in 2025, reflecting tradition and the significance of personalization for milestone events. Gifts represent another major segment, driven by holiday and special occasion demand. Smaller segments such as formal wear and parties are growing, indicating a broader shift toward self-expression and unique styling outside of traditional occasions. The industry’s ability to address both emotional and aspirational motivations supports ongoing application diversification.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-customized-jewelry
Frequently Asked Questions
Who are the key players in Global Customized Jewelry industry?
The key players in the Global Customized Jewelry industry include Tiffany & Co., Signet Jewelers, Pandora Jewelry, Bulgari (LVMH Group), and Cartier. These companies are renowned for their innovative designs, high-quality materials, large customer base, and global reach, making them leaders in the customized jewelry market segment.
What is the Global Customized Jewelry growth?
Global Customized Jewelry is witnessing robust growth, particularly fueled by increasing demand for personalized jewelry and online customization tools. For instance, Pandora Jewelry recorded significant sales growth in 2023 due to their expanded customization options and digital customer engagement strategies.
Which segment accounted for the largest Global Customized Jewelry share?
Personalized rings segment accounted for the largest share in Global Customized Jewelry market, owing to high demand for engagement, wedding, and commemorative rings. These applications drive the market as consumers seek unique ways to mark special occasions, leveraging custom engraving and gemstone selection for individual personalization.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global K-12 education market demonstrates strong and consistent revenue growth from 2020 to 2035. The transition to blended learning environments, heightened investment in educational infrastructure, and technology-led solutions fuel steady market expansion worldwide. In 2025, revenues are estimated at 178,000 million USD. By 2030, the market is projected to reach 260,000 million USD, accelerating further to 330,000 million USD by 2035. This robust upward trend is underpinned by continued demand for digital platforms, content, and data-driven instruction.
Read More - https://bussinessinsights.com/research-report/global-k-12-education-market
Curriculum solutions hold the largest application segment in the K-12 space for 2025, aligning with the sector's focus on delivering standardized, high-quality educational content. Assessment platforms are also vital, driven by the increasing acceptance of digital testing and analytics for student performance tracking. Learning management systems follow closely, supporting educators and administrators in streamlining instruction, communication, and data reporting. The expansion of analytics and communication tools reflects growing needs for actionable insights and stakeholder collaboration in both traditional and remote educational settings.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-k-12-education-market
Frequently Asked Questions
Who are the key players in Global K-12 Education Market industry?
Top players include Pearson, Blackboard Inc., Byju’s, K12 Inc., and McGraw-Hill Education. Pearson is a global leader in education publishing, while Byju’s is notable for its digital learning solutions. Blackboard and K12 Inc. provide virtual classroom platforms, and McGraw-Hill offers comprehensive curriculum development and assessment tools.
What is the Global K-12 Education Market growth?
The Global K-12 Education Market is experiencing robust growth, with a projected CAGR of over 7% from 2023 to 2028. Driven by increasing investments in EdTech, companies like Byju’s and Pearson have expanded their digital offerings, meeting the surging demand for online and blended learning programs.
Which segment accounted for the largest Global K-12 Education Market share?
The online learning segment dominated the market share, owing to the accelerated adoption of digital classrooms and e-learning platforms during the COVID-19 pandemic. Schools and institutions increasingly preferred online learning solutions offered by companies like Blackboard and K12 Inc. for continuous, flexible education delivery.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Automobile Cylinder Sleeve Market Hits USD 6.18 Billion in 2025, Projects 5.2% CAGR to 2032
By PW Consulting, 2026-09-07
Navigating the Next Wave: Strategic Intelligence for the Automobile Cylinder Sleeve Market 2026–2032
The global automotive powertrain component landscape is undergoing a structural transformation. For procurement leaders, engineering directors, and corporate strategists, the automobile cylinder sleeve market represents far more than a steady replacement cycle. It is a bellwether for material innovation, regulatory compliance, and the shifting center of gravity in global engine manufacturing. PW Consulting’s latest comprehensive research on this segment delivers the granular intelligence required to navigate the 2026–2032 forecast horizon with precision.
Worldwide Isolated RTD Input Module Market
As the industry transitions toward stricter emission standards, hybridized powertrains, and aggressive lightweighting mandates, cylinder sleeve specification has evolved from a commodity purchasing decision into a strategic engineering lever. Understanding where value will concentrate, which material technologies will gain commercial traction, and how the competitive hierarchy is crystallizing around proprietary casting methods requires a market study built on verified primary research and scenario-driven forecasting. This research preview outlines the analytical architecture of our full report, demonstrates how macroeconomic signals translate into actionable decision frameworks, and highlights the competitive dynamics that will separate market leaders from followers.
Hairdressing Training Heads Market
Readers will encounter a synthesis of historical performance data, forward-looking volume projections, and operational intelligence on the firms actively reshaping the supply base. No isolated percentages or region-by-region revenue tables are disclosed here; those granular breakdowns are preserved for the complete deliverable, where they are cross-referenced with capacity utilization rates, pricing architectures, and distributor network mappings. The objective of this preview is to establish the strategic terrain, clarify why disciplined intelligence consumption matters for 2026 planning cycles, and demonstrate the depth of analysis embedded in our methodology.
Worldwide Smart Grammar Editor Market
Market Trajectory: From Recovery Momentum to Sustained Expansion
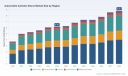
The automobile cylinder sleeve market has demonstrated remarkable resilience through a volatile decade of post-pandemic supply recalibration, fluctuating raw material costs, and divergent regional demand patterns. Historical tracking from 2020 through 2025 reveals a clear upward trajectory, with total market revenue climbing from approximately $3.71 billion to $6.18 billion. That growth arc reflects not only the restoration of global vehicle production volumes but also a structural shift in how engine builders approach cylinder bore durability, thermal management, and lifecycle cost optimization.
Looking toward the forecast window, the trajectory continues upward with measured confidence. Market valuations are projected to reach $6.29 billion in 2026, expanding steadily toward the $8.82 billion mark by 2032. This progression translates to a compound annual growth rate of 5.2 percent, a figure that signals sustainable expansion rather than speculative inflation. Growth of this nature is typically anchored by fundamental demand drivers: rising commercial vehicle utilization in developing economies, sustained passenger car fleet refreshes in mature markets, and the persistent need for upgraded sleeve solutions as internal combustion platforms are refined for efficiency and longevity.
For corporate decision-makers, a 5.2 percent CAGR carries strategic implications beyond top-line projections. It indicates a market where share gains are earned through technical differentiation and supply reliability rather than price compression alone. It also suggests that capacity planning, tooling investment, and material sourcing agreements negotiated in 2026 will have multi-year payoff horizons. Companies that treat the forecast period as a static backdrop risk underinvesting in advanced casting capabilities or misallocating working capital toward segments where margin compression is most acute. The full report decomposes this trajectory by volume-to-value ratios, regional capacity shifts, and application-specific growth vectors, enabling leadership teams to align capital deployment with the most defensible pockets of expansion.
Segmentation Architecture: Where Material, Design, and Application Intersect
Cylinder sleeve demand does not behave uniformly across the automotive ecosystem. The segment is shaped by intersecting technical requirements, cost structures, and manufacturing footprints that determine which product architecture wins in a given application. The research framework dissects the market through three primary segmentation lenses, each carrying distinct strategic implications for suppliers, OEMs, and tier-one integrators.
Material Technology Divergence
Material selection remains the foundational decision point in cylinder sleeve engineering. The historical dominance of traditional cast iron reflects its proven wear resistance, thermal stability, and cost-effectiveness in high-volume applications. Yet the landscape is increasingly textured by the emergence of aluminum alloy formulations and specialized steel variants designed to meet tighter dimensional tolerances and reduced component mass. The interplay between these material categories is not a simple substitution dynamic; rather, it represents a portfolio optimization challenge.
Cast iron continues to anchor a substantial portion of the installed base, particularly where durability under high thermal loads and long service intervals are non-negotiable. Simultaneously, industry trajectory analysis points toward sustained growth in lightweight aluminum and composite alloy architectures, driven by fuel economy targets and the broader regulatory push for vehicle weight reduction. Aluminum-based sleeves, often paired with specialized coatings and surface treatments, enable thermal transfer optimization while contributing to overall engine mass savings. Steel variants occupy a more specialized position, typically deployed where specific load profiles or mating surface requirements demand superior tensile characteristics.
Strategic buyers evaluating material roadmap alignment must look beyond headline performance claims. The research delves into how alloy formulations interact with casting methodologies, how surface finishing tolerances influence runout and friction behavior, and how material supply chains are being restructured to mitigate volatility in metallurgical input pricing. By isolating the value pools within each material category, the report equips engineering and procurement teams with the criteria needed to negotiate supply agreements that balance performance assurance with cost predictability.
Liner Configuration and Application Mapping
Beyond material chemistry, the physical configuration of the sleeve—whether dry, wet, or finned—fundamentally alters the thermal management and assembly architecture of the engine block. Dry liners, seated directly into the cylinder block and relying on the block material for coolant isolation, remain prevalent in applications where structural rigidity and simplified assembly are prioritized. Wet liners, which interface directly with the cooling jacket, offer superior heat extraction but introduce sealing and corrosion management complexities that demand higher precision manufacturing. Finned configurations occupy niche positions where enhanced surface area for thermal dissipation is required under extreme operating conditions.
Application segmentation further differentiates demand intensity and specification requirements. Passenger car platforms account for the largest concentration of sleeve consumption, reflecting the sheer multiplicity of global vehicle platforms and the ongoing refresh cycles required to meet evolving emission norms. Commercial vehicle segments—both light and heavy—present different engineering constraints, with heavy-duty applications emphasizing extended service life, resistance to particulate-induced abrasion, and tolerance for sustained high-load operation. Two-wheeler platforms, while representing a smaller revenue footprint, demand cost-optimized solutions that can be produced at high velocity with minimal tolerance variability.
The full report maps these configuration and application intersections against regional manufacturing footprints, revealing where production localization incentives, logistics cost structures, and OEM sourcing strategies are reshaping supply routes. Rather than presenting static regional shares, the analysis emphasizes the flow of capability: which manufacturing clusters are expanding advanced centrifugal casting capacity, which regions are seeing increased local content requirements, and how tier-one suppliers are repositioning their plant networks to serve emerging platform allocations. This dynamic view allows strategists to anticipate sourcing friction points and identify partnership opportunities before capacity constraints become pricing leverage for incumbents.
Regulatory Pressure and Engineering Imperatives
Regulatory frameworks are no longer peripheral compliance costs; they are primary drivers of material specification and dimensional precision in cylinder sleeve design. The progressive tightening of emission standards across major automotive markets has cascading effects on combustion chamber tolerances, piston ring dynamics, and the thermal fatigue characteristics expected of cylinder liners over extended service intervals.
Standards such as Euro 6d and Bharat Stage VI mandate tighter combustion chamber tolerances and longer service intervals, directly elevating the requirement for cylinder liners that exhibit superior thermal fatigue resistance and dimensional stability under repeated heating and cooling cycles. A sleeve that distorts under thermal load compromises combustion efficiency, increases oil consumption, and accelerates wear across reciprocating components. These pressures push material and coating innovation from optional enhancement to baseline requirement.
Complementing emissions mandates, engineering standards such as SAE J2236 define material specifications for engine cylinder liners, providing a formalized reference for metallurgical composition, casting integrity, and surface performance criteria. Adherence to such standards not only mitigates liability in warranty and quality dispute scenarios but also streamlines the validation process when introducing new sleeve architectures to engine platforms that must satisfy multiple regulatory jurisdictions.
The research integrates these regulatory and standards-driven dynamics into a forward-looking risk matrix. Rather than treating compliance as a static checkpoint, the analysis examines how evolving test protocols, extended durability expectations, and cross-market alignment of emission thresholds are reshaping the acceptable performance envelope for cylinder sleeves. This perspective is critical for organizations that must justify tooling investments or material transitions to internal stakeholders, as it anchors engineering decisions in verifiable regulatory trajectories rather than speculative assumptions.
Competitive Landscape: Concentration, Differentiation, and Strategic Positioning
The automobile cylinder sleeve market exhibits a moderate concentration structure, with leading firms commanding disproportionate influence through proprietary casting technology, long-standing OEM qualifications, and globally distributed production footprints. The competitive hierarchy is not defined solely by scale; it is increasingly shaped by the ability to deliver application-specific liner architectures that satisfy stringent performance criteria while maintaining cost competitiveness across high-volume and specialty segments.
Incumbent Profiles and Capability Positioning
Several established manufacturers anchor the competitive landscape, each leveraging distinct technical strengths and geographic reach. MAHLE GmbH, headquartered in Stuttgart, operates a vertically integrated approach to centrifugal cast cylinder liners, producing in-house solutions for passenger cars, commercial vehicles, and engines extending up to 460 mm piston diameter. Their emphasis on high-strength materials and low-wear running surfaces positions them as a supplier of choice for applications where dimensional consistency and durability under sustained load are critical.
Tenneco Inc., based in Ann Arbor, Michigan, has built its cylinder sleeve portfolio around advanced material optimization, coating engineering, and design precision aimed at enhancing running surfaces, heat transfer efficiency, and friction reduction. Their capability spans light-duty, heavy-duty, and large-bore engines, reflecting a breadth of application expertise that aligns with diverse OEM performance targets.
In the Japanese market, TPR Co., Ltd. has differentiated itself through cast-in liners utilizing patented AsLock® technology delivered via centrifugal casting, alongside thin-wall and wet liner configurations engineered for compatibility with aluminum engine blocks. Their solutions serve Japanese OEMs across gasoline and diesel applications, illustrating how localized technical differentiation can secure long-term supply relationships within concentrated OEM ecosystems.
Kolbenschmidt GmbH, operating from Frankfurt, integrates cylinder liners into broader piston system offerings for passenger cars and commercial vehicles, emphasizing high-quality construction aligned with original equipment specifications. This systems-oriented approach enables coordinated engineering across reciprocating components, reducing interface variability and simplifying validation workflows for engine manufacturers.
The competitive field also includes regionally significant players such as Zhongyuan Cylinder Liner Company Limited in China, which supplies the GKNZ-branded portfolio for automotive and industrial engines, and Aichi Machine Industry Co., Ltd. in Aichi, Japan, whose cylinder liner production supports a range of engine applications. These firms illustrate the importance of regional manufacturing depth and localized engineering responsiveness in markets where supply chain proximity, cost structures, and OEM relationship dynamics diverge from globalized procurement models.
Recent Developments and Industry Reconfiguration
Market structure is not static; it evolves through product introductions, corporate restructuring, and shifts in technology emphasis. Recent industry activity signals ongoing realignment in how cylinder sleeve capabilities are packaged and delivered. In early 2025, Federal-Mogul Powertrain released a new silicon-aluminum alloy composite cylinder liner designed to meet evolving engine demands, reflecting the broader industry exploration of composite formulations that balance thermal performance with weight efficiency.
In parallel, Nippon Piston Ring Co., Ltd. announced plans to merge with Riken, forming NPR-RIKEN Corporation to enhance combined capabilities in piston rings and cylinder liners. This consolidation underscores a recurring theme in component manufacturing: the increasing value of integrated reciprocating system expertise, where liner, ring, and piston dynamics are engineered as a synchronized performance package rather than isolated parts.
The research evaluates these developments not as isolated news items but as structural indicators of where technical investment and M&A activity are concentrating. By examining the interplay between product launches, corporate consolidation, and capability expansion, the report enables strategists to anticipate shifts in supplier bargaining power, identify potential disruptions in established supply routes, and assess which firms are likely to strengthen their qualification positions with major OEMs over the forecast horizon.
What the Full Report Delivers: Analytical Structure and Decision Utility
The complete PW Consulting research deliverable is structured to move from strategic context to operational detail, ensuring that every analytical layer connects to a concrete decision application. The report combines historical reconstruction, multi-variable forecasting, segmentation cross-analysis, and competitive profiling into a cohesive intelligence asset designed for executive planning, engineering roadmap alignment, and procurement strategy refinement.
Core Report Components
- Comprehensive market size reconstruction spanning the 2020–2025 historical window, with methodological transparency on data sourcing, triangulation approaches, and revision history to establish a credible baseline for forecasting.
- Scenario-based projections through 2032 that account for base-case, accelerated, and constrained growth pathways, allowing leadership teams to stress-test capacity planning and sourcing commitments against alternative macroeconomic and industry volume outcomes.
- Detailed segmentation analysis across material type, liner configuration, vehicle type, and geographic production distribution, with volume-to-value mapping that clarifies where revenue intensity diverges from unit volume and how pricing architectures differ across application categories.
- Competitive benchmarking that evaluates firm positioning through technology differentiation, capacity footprint, OEM qualification breadth, and recent strategic moves, providing a comparative lens for partnership evaluation and competitive response planning.
- Regulatory and standards impact assessment that translates emission mandates, material specification frameworks, and durability expectations into actionable engineering and procurement criteria.
- Supply chain and raw material dynamics review that examines casting feedstock availability, alloy pricing volatility, and logistics considerations influencing regional sourcing decisions.
- Identification of high-growth subsegments and emerging application vectors, supported by qualitative indicators that signal where demand intensity is likely to outpace incumbent capacity or where new material architectures may create displacement opportunities.
Intended Audience and Use Cases
This research is designed for multiple functional stakeholders who require synthesized intelligence rather than raw data tables. Corporate strategists can use the segmentation and competitive frameworks to evaluate market entry potential, partnership suitability, and portfolio alignment. Procurement and supply chain leaders can leverage the material and configuration analysis to structure sourcing negotiations that balance performance assurance with cost management across multi-year agreements. Engineering and product development teams benefit from the regulatory and standards mapping, which clarifies which technical thresholds are likely to become baseline requirements and where innovation headroom remains available. Investors and market analysts can utilize the forecast architecture and competitive positioning assessment to evaluate sector attractiveness, margin sustainability, and consolidation probability.
Connecting Intelligence to 2026 Decision Cycles
The strategic value of market intelligence is realized not through passive consumption but through active integration into planning cycles. As organizations finalize 2026 capital allocations, sourcing strategies, and engineering roadmaps, the automobile cylinder sleeve market presents a landscape where disciplined analysis directly informs competitive positioning. The 5.2 percent CAGR trajectory signals a market large enough to support multiple specialized players yet concentrated enough that capability gaps translate quickly into lost qualification opportunities. Material innovation, particularly around lightweight aluminum and composite formulations, is reshaping specification conversations, while regulatory tightening continues to elevate the importance of dimensional stability and thermal fatigue performance.
Companies that embed granular segmentation understanding, competitive capability mapping, and regulatory trajectory awareness into their 2026 decision frameworks will be better positioned to negotiate from a place of informed confidence. They will be able to identify which supplier relationships merit long-term commitment, which material transitions warrant accelerated validation investment, and which regional capacity shifts may alter logistics cost structures or lead-time reliability. The full research report preserves the detailed regional revenue distributions, application-specific growth vectors, and competitive share constructs required to execute these judgments with precision, ensuring that strategic conclusions rest on verified data rather than approximation.
Accessing the Complete Intelligence Asset
This preview has outlined the analytical terrain, demonstrated the interplay between macro trajectory and micro engineering requirements, and highlighted the competitive dynamics that will define the market structure through 2032. The complete PW Consulting Automobile Cylinder Sleeve Market research report builds on this foundation with granular segmentation data, regional capacity and revenue distributions, pricing and margin analysis, detailed company profiles, and forward-looking scenario modeling. All core tables, regional breakdowns, application-level growth vectors, and material segment revenue constructs are presented in the full deliverable to support rigorous strategic review.
For organizations preparing 2026 sourcing strategies, capacity plans, or technology investment roadmaps, the complete report provides the evidentiary depth needed to convert market observation into executable strategy. Readers seeking the full segmentation matrices, regional production and consumption distributions, competitive share constructs, and scenario-based forecast tables are encouraged to access the complete report at the source webpage, where the complete dataset and accompanying analytical commentary are available for download and internal distribution.
For detailed analysis of this topic, please visit the official page: Automobile Cylinder Sleeve Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Cold Press Juicer Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
Market revenue for global cold press juicers has seen steady growth from 2020 through 2025, attributed to increased adoption across consumer categories and innovation in product technology. The momentum is expected to continue, with projected revenue reaching 4,700 million USD by 2035, reflecting strong CAGR across all major regions. Key contributors include robust sales in Asia Pacific, North America, and Europe.
Read More - https://bussinessinsights.com/research-report/global-cold-press-juicer
Residential applications hold the largest share of the cold press juicer market in 2025, driven by increased health consciousness and home juicing trends. Commercial establishments, including juice bars and cafes, represent significant growth areas, capitalizing on the demand for premium juice experiences. Industrial applications are gradually rising, especially in large-scale beverage manufacturing, but continue to lag behind direct consumer and commercial segments.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-cold-press-juicer
Frequently Asked Questions
Who are the key players in Global Cold Press Juicer industry?
The top 5 players in the Global Cold Press Juicer industry include Hurom, Kuvings, Omega, Philips, and Breville. These companies are renowned for their strong product innovation, global distribution networks, and focus on health-conscious consumers, making them leaders in the cold press juicer market.
What is the Global Cold Press Juicer growth?
The Global Cold Press Juicer market is experiencing steady growth due to increasing health awareness and demand for nutrient-rich juices. In 2023, companies like Kuvings reported significant sales growth driven by the popularity of at-home wellness products and innovative appliance features.
Which segment accounted for the largest Global Cold Press Juicer share?
The household application segment held the largest market share in the Global Cold Press Juicer market. Growing adoption of healthy lifestyles and rising demand for convenient home appliances are fueling household juicer sales, making this segment the leading contributor to market revenue.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
The global pedestal fans market is projected to deliver robust revenue growth from 2020 through 2035. The market generated USD 1,620 Million in revenue for the year 2021, rising sharply due to core demand in residential segments and further uplifted by commercial adoption in the subsequent years. The anticipated compound annual growth rate (CAGR) remains strong, as technological advancements, the introduction of smart and energy-efficient products, and penetration in developing markets drive sustainable sales growth. Revenues are expected to surpass USD 3,900 Million by 2030 and continue upward, signaling the market's resilience and adaptability amid evolving consumer needs.
Read More - https://bussinessinsights.com/research-report/global-pedestal-fans
Application usage for pedestal fans in 2025 is led by indoor settings, with the majority of demand sourced from household bedrooms and living spaces. Commercial use, including offices and retail spaces, follows closely, driven by the need for affordable, movable cooling systems. Demand for outdoor pedestal fans is surging, particularly in hospitality and event sectors, supported by weather-resistant innovations. The dynamic application landscape is further influenced by the multipurpose utility of modern pedestal fans, which feature adjustability and portability, making them suitable for transitional space cooling in both residential and commercial environments.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-pedestal-fans
Frequently Asked Questions
Who are the key players in Global Pedestal Fans industry?
Key players include Crompton Greaves, Havells India, Usha International, Midea Group, and Orient Electric. These companies dominate the market with extensive distribution networks, innovative product launches, strong brand presence, and strategic partnerships in emerging economies to cater to diverse residential and commercial needs globally.
What is the Global Pedestal Fans growth?
The global pedestal fans market has experienced steady growth, with recent expansion attributed to increasing demand for energy-efficient cooling solutions. For example, Orient Electric reported a surge in fan sales in 2023 due to rising temperatures and enhanced urbanization, leading to a robust market trajectory.
Which segment accounted for the largest Global Pedestal Fans share?
Residential applications dominate the global pedestal fans market, accounting for the largest share. The demand arises from growing urban households, rising temperatures, and affordability over air conditioning. Continuous innovation in design and features by top brands attracts more consumers to the residential segment.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: In-Building Wireless Market to Hit $49.3M by 2032, 11.8% CAGR
By PW Consulting, 2026-09-07
The 2026 In-Building Wireless Market: Strategic Imperatives for Enterprise Decision-Makers
The Connectivity Imperative Driving Next-Generation Infrastructure
The modern enterprise operates on a foundation of seamless, high-capacity connectivity. As organizations continue to digitize operations, deploy dense IoT ecosystems, and expect uninterrupted wireless performance from staff and visitors alike, the physical and operational architecture of in-building wireless (IBW) networks has transitioned from a tactical facility requirement to a core strategic asset. The trajectory of the IBW market through 2026 confirms that institutional attention is well placed. Following a sustained expansion cycle between 2020 and 2025, the sector reached a valuation of approximately 22.58 million USD at the close of the base year. From that starting point, the market is projected to advance through the 2026–2032 forecast horizon, with 2026 opening at an estimated 25.35 million USD and climbing steadily toward 49.3 million USD by 2032. This progression reflects a compound annual growth rate of 11.8 percent, signaling that infrastructure planners and corporate decision-makers must treat IBW investment as a long-term capability rather than a periodic refresh cycle. The acceleration is not merely a reflection of incremental demand. It is driven by structural shifts in how facilities consume wireless spectrum, how operators monetize indoor coverage, and how enterprises balance performance requirements against operational complexity. Understanding the forces shaping this expansion requires moving beyond headline valuations and examining the architecture of demand, the competitive dynamics defining supply, and the regulatory and technical environment that determines deployment feasibility. Our latest In-Building Wireless Market research is designed precisely for that purpose. It translates macroeconomic momentum into actionable positioning, enabling technology buyers, network architects, and commercial strategy teams to align capital allocation with the specific conditions that will govern the next several years of deployment.
Automatic Sealing and Packing Machine Market
Market Trajectory and the Structural Forces Behind the Growth Curve
The expansion recorded between 2020 and 2025 established a clear baseline for understanding today’s demand environment. Over that five-year span, the market moved from 12.93 million USD to 22.58 million USD, demonstrating resilience through shifting macroeconomic conditions and growing comfort with advanced indoor wireless architectures. The current forecast period extends that trend into the late 2020s and early 2030s, with the market expected to reach 28.19 million USD in 2027, 32.51 million USD in 2028, and continued appreciation through 34.5 million USD in 2029, 39.42 million USD in 2030, 44.38 million USD in 2031, and 49.3 million USD in 2032. These figures illustrate a market that is not simply rebounding but compounding, with each forecast interval building on prior capacity gains, technology maturity, and broadened enterprise adoption. The 11.8 percent CAGR embeds several underlying drivers that our research unpacks in detail. First, the shift toward higher-density wireless environments is accelerating across sectors that historically underinvested in indoor coverage optimization. Second, the operational case for distributed wireless architectures is becoming more compelling as facilities seek to support simultaneous high-throughput applications, real-time analytics, and massive device connectivity without degrading performance. Third, the commercial logic of shared and neutral host deployment models is reducing the friction that previously constrained enterprise adoption, particularly in properties where multiple stakeholders or carriers must coexist on a single infrastructure footprint. Our report situates these trends within a rigorous analytical framework. It tracks revenue progression across the historical and forecast windows, isolates the variables that materially influence deployment velocity, and identifies where market participants stand to capture value as architectural preferences evolve. Importantly, the analysis is structured to support decision-making at the procurement, investment, and competitive positioning levels. By understanding how the overall revenue curve behaves and what conditions sustain it, strategic teams can forecast infrastructure spend with greater precision and avoid the common pitfall of reacting to technology hype rather than deploying resources against verified demand patterns.
Electronic Contract Management Market
Core Segmentation Dynamics Reshaping Deployment Architecture
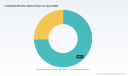
The composition of market growth reveals a landscape in which technology type and application environment interact to create distinct deployment priorities. Our research examines technology segmentation across Distributed Antenna Systems, Small Cell architectures, and Distributed Radio Systems, along with application segmentation spanning Commercial Campuses, Hospitality, Transportation and Logistics, Entertainment and Sports Venues, Industrial Manufacturing, Education, Government, and Healthcare. These categories are not isolated demand pools. They form a set of interdependent considerations that determine which architecture, deployment model, and vendor capability set will deliver the strongest return for a given facility profile. Technology choices increasingly reflect the need to reconcile coverage breadth with capacity granularity. Some environments favor centralized distribution approaches that simplify signal management across large footprints, while others rely on more granular deployment nodes that offer rapid scaling and localized performance control. The report details the circumstances in which each architecture delivers the most favorable balance of capital efficiency, maintenance burden, and performance reliability. On the application side, the demand profile is equally varied. Hospitality and entertainment venues continue to prioritize seamless connectivity as a core guest experience and operational enabler. Transportation and logistics environments demand robust wireless performance in spaces with challenging propagation characteristics and high equipment density. Industrial manufacturing contexts emphasize mission-critical reliability and integration with operational technology ecosystems. Education, government, and healthcare facilities face their own combinations of capacity requirements, regulatory considerations, and multi-stakeholder coordination demands. The commercial campus segment sits at the intersection of multiple use cases, often requiring a flexible architecture that can support both enterprise productivity and visitor-facing service expectations. Our segmentation analysis goes further than descriptive classification. It evaluates how these demand categories map to deployment economics, where architectural choices influence total cost of ownership, and how facility characteristics shape the relative attractiveness of different vendor offerings. Decision-makers who rely on generic wireless assumptions often underestimate the importance of environment-specific design. This research corrects that gap by providing a structured view of how application profiles influence both short-term deployment decisions and longer-term network evolution. By focusing on the practical relationships between segment characteristics and architectural viability, the report enables teams to prioritize investment where it produces the most durable operational outcomes.
Worldwide Milling Automation Market
Competitive Dynamics and the Strategic Positioning of Leading Providers
The IBW market is characterized by a concentration of capability among a defined group of established and emerging providers, and understanding their strategic behavior is essential for procurement planning and competitive assessment. Our research includes detailed profiles of key participants, with particular attention to companies whose recent product and positioning moves signal where the market is heading. Moso Networks, based in the United States, has built a profile around private 5G and neutral host solutions for in-building wireless. Its offering emphasizes plug-and-play indoor and outdoor radios designed to function as rapid DAS replacements, supported by CBRS capability and cloud-based management. This positioning reflects a broader movement toward reducing deployment friction while preserving flexibility in operator and enterprise use cases. In January 2026, Moso Networks advanced this direction by launching the Chorus P5G solution in partnership with Ataya, an initiative intended to simplify private 5G deployment to a 5G radio and secure cloud connection for indoor and outdoor use. The move underscores an emerging expectation that private wireless deployments must be manageable without requiring extensive integration overhead. ANDREW, operating under Amphenol Corporation and also headquartered in the United States, provides a complementary but distinct set of capabilities. Its portfolio spans ERA digital DAS, ONECELL small cells, and in-building wireless solutions oriented toward 5G coverage, multi-operator connectivity, and mission-critical private networking. The company’s focus on multi-operator and neutral host models positions it within the infrastructure layer that serves venues and enterprises seeking shared access arrangements rather than single-operator exclusivity. In January 2026, ANDREW received honors at the Small Cell Forum awards for innovation in indoor and outdoor wireless solutions and neutral host and multi-operator models. The recognition highlighted a world’s first DAS deployment with full direct digital connectivity to three leading RAN vendors in a live stadium, an achievement that illustrates the increasing feasibility of high-performance, multi-vendor indoor environments. SOLiD, based in South Korea, contributes another strategic angle through modular and scalable DAS and in-building wireless solutions designed for venues and enterprises that must deliver 5G coverage and capacity in challenging environments. Its emphasis on modularity aligns with the broader market push toward architectures that can expand incrementally as coverage or capacity requirements change. These company profiles do not exist in isolation. They reflect a competitive environment in which vendors are differentiating through deployment simplicity, multi-operator enablement, modularity, and cloud management maturity. Our report maps these differentiators against the conditions that matter most to buyers, including integration complexity, operational overhead, and the ability to support evolving spectrum and service requirements. In parallel, the analysis tracks wider industry signals that shape competitive dynamics. The Wireless Infrastructure Association highlighted Nextivity Inc. in January 2026 as a key player in in-building wireless networks, with emphasis on ROI measurement and unified network approaches for schools and enterprises. Such visibility indicates that competitive positioning is increasingly tied to measurable outcomes and cross-environment network unification, not solely to hardware capability. The market concentration context further reinforces the importance of strategic supplier evaluation. With a CR3 of 52.6 percent and a CR5 of 67.0 percent, the landscape is concentrated enough that vendor selection has meaningful implications for negotiation leverage, integration risk, and long-term support continuity. Our research supports more disciplined supplier assessment by aligning provider capabilities with the deployment scenarios in which they are most likely to succeed.
Inside the Report: Operational Content Designed for Execution
Strategic Decision Support Across the Investment Lifecycle
A market study earns its place in an enterprise workflow only if it supports concrete actions. This report is built around that expectation. It provides a structured foundation for evaluating where in-building wireless investment should be prioritized, how deployment architecture should be selected, and what vendor and partnership strategies are most likely to deliver value across the forecast horizon. The content is organized so that readers can move from high-level market context to operational considerations without losing analytical discipline. Rather than offering generic technology overviews, the report ties market behavior to procurement and planning decisions that matter in 2026 and beyond.
Detailed Architecture and Deployment Considerations
The report examines the physical and operational realities that determine whether an in-building wireless investment performs as intended. Topics include the integration requirements associated with existing fiber optic networks and signal sources, with emphasis on practical factors such as PIM mitigation and power optimization. These details are not ancillary. They directly affect deployment reliability, long-term maintenance burden, and the feasibility of achieving consistent coverage in environments where signal propagation is constrained by structure, density, or interference. The analysis also addresses how different architectural approaches influence integration effort and operational control, enabling teams to anticipate both the capital and operational implications of design choices before commitments are made.
Application, Technology, and Regional Demand Context
Demand does not distribute evenly across sectors or deployment environments. The report maps how application profiles shape performance expectations, investment urgency, and architectural suitability. At the same time, it provides regional context that helps decision-makers understand where demand intensity, infrastructure readiness, and competitive activity converge. Rather than presenting narrow percentage breakdowns or isolated submarket figures, the research integrates regional and application context into a broader narrative of where growth is accelerating and why. This approach is deliberate. It allows readers to grasp the relative importance of different demand pools and geographic environments without reducing the analysis to a static table of splits. The result is a market map that is useful for strategy formulation, sales targeting, investment prioritization, and competitive positioning.
Regulatory, Spectrum, and Operational Environment Factors
Technology selection cannot be separated from the regulatory and spectrum context in which it operates. The report incorporates the January 2026 FCC action through FCC 26-1, which enabled more flexible operation of low-power indoor unlicensed devices in the 6 GHz band, including building loss considerations within automated frequency coordination. This development matters because it affects how unlicensed and lightly licensed spectrum can be used to complement licensed deployments and how automation tools influence indoor frequency management. The report also addresses broader FCC activity in 2026 related to spectrum abundance in space operations and the modernization of sharing rules for satellite broadband, both of which carry implications for spectrum access and the wider environment in which in-building wireless enhancements are planned. In addition, the analysis notes compliance and procurement realities relevant to public-sector and infrastructure buyers, including alignment with Build America Buy America requirements for certain products as of early 2026. These regulatory and operational inputs are not treated as isolated news items. They are integrated into the practical side of deployment planning, helping readers assess where flexibility is increasing, where constraints remain, and how those conditions influence vendor selection, architecture design, and total project risk.
Why This Research Matters for 2026 Strategy
Translating Market Momentum into Capital and Vendor Strategy
Organizations evaluating in-building wireless investment face a common challenge: market momentum is visible, but the path from growth headline to deployment decision is not. The market’s expansion from 12.93 million USD in 2020 to 22.58 million USD in 2025, and its projected rise through the forecast window toward 49.3 million USD by 2032 at an 11.8 percent CAGR, provides a strong signal that indoor wireless infrastructure is moving up the priority stack. But signal strength alone does not define strategy. Decision-makers still need clarity on which application contexts justify accelerated investment, which technology profiles align with specific facility conditions, and how competitive and regulatory developments alter the risk and reward calculus of different deployment approaches. This report is designed to answer those questions with enough depth to guide action. It helps procurement and network teams compare architectural options against real operating conditions, supports executive teams in communicating why indoor wireless investment deserves sustained attention, and equips strategy functions with the context needed to evaluate vendor promises against market reality. In an environment marked by concentration, rapid product iteration, and evolving spectrum possibilities, disciplined research is not a luxury. It is the mechanism that separates informed planning from reactive purchasing.
What the Report Enables Decision-Makers to Do
The research is structured to support a set of recurring strategic tasks. It helps organizations benchmark current infrastructure assumptions against the market direction reflected in the 2026–2032 forecast. It supports vendor evaluation by connecting provider profiles and recent developments to the operational requirements that buyers are likely to face. It clarifies how application environments differ in their connectivity demands and what that means for architecture, timing, and budget sequencing. It also gives leadership teams a shared analytical baseline for discussions about capital planning, partnership strategy, and long-term network evolution. By focusing on usable intelligence rather than exhaustive disclosure of every submarket figure, the report preserves analytical depth while directing readers to the full dataset and supporting detail where they can refine their own models and internal assumptions.
A Strategic Entry Point for Deeper Intelligence
In-building wireless is no longer a niche infrastructure category. It is a strategically significant layer of enterprise connectivity that intersects with private networking, multi-operator access, venue experience, industrial digitization, and facility modernization. The research presented here is intended for teams that need to understand the market well enough to act with confidence in 2026 and to plan for the changes expected through 2032. The macro trajectory, segmentation dynamics, vendor movements, and regulatory context described in this article establish the foundation. The full report extends that foundation into a more granular analytical environment, providing the detailed data, segmentation detail, and scenario-based interpretation that decision-makers need to convert market insight into execution. For organizations seeking to align infrastructure strategy with where the IBW market is actually heading, this research offers the evidence base and interpretive framework required to move forward with precision.
For detailed analysis of this topic, please visit the official page: In-Building Wireless Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Asia-Pacific Exhaust Fans Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
Asia-Pacific exhaust fans market revenue illustrates an upward trend from 2020 through 2035, with robust CAGR anticipated between 2025 and 2030 driven by urban construction, regulatory reforms, and health concerns. Estimated market size is $5,400 Million in 2025, projected to surpass $10,300 Million by 2035. Leading countries such as China and India contribute significantly, propelled by large-scale residential and industrial projects. Dynamic investments and shifting consumer preferences for sustainable solutions underpin this positive trajectory.
Read More - https://bussinessinsights.com/research-report/asia-pacific-exhaust-fans
Residential usage leads the applications segment of the Asia-Pacific exhaust fans market in 2025, a testament to rapid urban housing development and evolving indoor air quality standards. Commercial installations, including offices and retail stores, follow close behind as businesses prioritize employee wellness. The industrial sector, encompassing manufacturing, food & beverage, and automotive facilities, accounts for considerable share, driven by compliance with safety and emission norms. Healthcare settings, responding to heightened post-pandemic hygiene requirements, are emerging as a fast-growing niche.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/asia-pacific-exhaust-fans
Frequently Asked Questions
Who are the key players in Asia-Pacific Exhaust Fans industry?
Key players in the Asia-Pacific Exhaust Fans industry include Panasonic Corporation, Delta Electronics, Mitsubishi Electric, Crompton Greaves, and Ventilation Engineering Company. These companies are recognized for their innovation, extensive product ranges, and strong distribution networks that cater to both commercial and residential ventilation needs across diverse Asia-Pacific markets.
What is the Asia-Pacific Exhaust Fans growth?
The Asia-Pacific Exhaust Fans market has witnessed notable growth, driven by increasing urbanization and commercial infrastructure. In 2023, Panasonic Corporation reported double-digit sales growth owing to heightened demand for energy-efficient ventilation solutions in emerging economies such as India and Southeast Asia.
Which segment accounted for the largest Asia-Pacific Exhaust Fans share?
The residential segment holds the largest share of the Asia-Pacific Exhaust Fans market. This is attributed to rapid urbanization, rising awareness of indoor air quality, and increased construction of apartments and housing complexes, especially in countries like China and India, driving strong residential demand.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
Asia-Pacific Water Purifier Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
The revenue trajectory of the Asia-Pacific water purifier market underscores strong, sustained growth. Estimated at $7,800 million in 2025, the market is set to reach nearly $20,600 million by 2035, with a CAGR approaching 10%. Growth is spurred by rapid urbanization, rising health concerns, and technological advances. China and India remain growth engines, followed by fast-expanding Southeast Asian economies. Product innovation and evolving consumer lifestyles continue to drive revenue in both replacement and new installation segments.
Read More - https://bussinessinsights.com/research-report/asia-pacific-water-purifier
Residential applications account for the majority share of water purifier adoption in 2025, as urban populations prioritize health and safe drinking water at home. The commercial sector is expanding rapidly with the installation of advanced filtration solutions in offices, hotels, and restaurants. Healthcare and educational institutions also represent key application areas, driven by stricter hygiene standards and regulatory policies. Industrial adoption lags due to the need for customized solutions. As more end-users realize the importance of water quality management, market expansion is expected across diverse application segments over the next decade.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/asia-pacific-water-purifier
Frequently Asked Questions
Who are the key players in Asia-Pacific Water Purifier industry?
The top five players in the Asia-Pacific Water Purifier market include Kent RO Systems, Coway, Panasonic Corporation, LG Electronics, and Eureka Forbes. These companies are recognized for their extensive product portfolios, strong distribution networks, innovative technologies, and focus on water quality improvements across urban and rural markets in the region.
What is the Asia-Pacific Water Purifier growth?
The Asia-Pacific Water Purifier market has experienced steady growth, driven by increasing water contamination and health awareness. For instance, in 2023, Kent RO Systems reported a significant sales increase in India, attributed to greater demand for advanced filtration systems and urbanization, indicating robust market expansion in the region.
Which segment accounted for the largest Asia-Pacific Water Purifier share?
The residential segment holds the largest share in the Asia-Pacific Water Purifier market. With rising health awareness and concerns over tap water quality, households increasingly adopt water purifiers, particularly in urban areas. Companies like Eureka Forbes and Panasonic have expanded their residential product lines to cater to this growing demand.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com
PW Consulting: Light Gauge Steel Market to Hit USD 42.7B in 2025, Grow at 5.73% CAGR to USD 63.02B by 2032
By PW Consulting, 2026-09-07
Navigating the Light Gauge Steel Market: A Strategic Intelligence Brief for 2026 Decision-Makers
The construction materials landscape is undergoing a structural recalibration. As decarbonization mandates tighten, labor constraints persist, and prefabrication demands accelerate, Light Gauge Steel (LGS) has moved from a niche alternative to a strategic core component in modern building systems. For executives, investors, and procurement leaders operating in 2026, the question is no longer whether LGS will gain traction but how to position portfolios, supply chains, and go-to-market strategies against a rapidly consolidating and innovation-driven market.
Worldwide Constant Temperature Electric Blanket Market
PW Consulting's latest Light Gauge Steel Market research study is engineered to translate macro trajectories into executable intelligence. Rather than offering static snapshots, this report maps the operational, regulatory, and competitive forces that will define market behavior between 2026 and 2032. The brief below outlines the strategic architecture of the study, demonstrates how macro indicators contextualize today's decisions, and highlights the competitive and regulatory signals that are already reshaping the field. Complete segmentation breakdowns, regional deployment matrices, and company-level performance metrics are reserved for the full report, where they can be cross-referenced against your internal benchmarks and growth models.
Worldwide Dry Suit Market
Why 2026 Imposes a Different Decision Rhythm
The post-pandemic construction cycle has matured into a phase defined by cost discipline, material traceability, and engineered efficiencies. Organizations can no longer rely on historical volume growth alone to justify capacity expansion or product development. Instead, they must interpret how demand shifts across building types, how regional procurement ecosystems evolve, and how standard-setting bodies influence specification behavior.
Worldwide Natural Creatine Market
Our research window opens from a 2025 base year that captures the market at a meaningful inflection point. Historical tracking from 2020 through 2025 demonstrates a sustained upward trajectory, with the overall market expanding from approximately 29.0 billion USD in 2020 to 42.71 billion USD in 2025. That progression reflects more than cyclical recovery; it indicates structural adoption across multiple construction verticals, supported by lighter material handling, faster erection timelines, and increasing compatibility with off-site manufacturing workflows.
Looking forward, the forecast horizon through 2032 projects continued expansion at a CAGR of 5.73 percent, with the market advancing from 44.71 billion USD in 2026 toward 63.02 billion USD by 2032. These headline numbers matter because they reframe the scale of opportunity relative to capital allocation cycles. A mid-single-digit compound trajectory in a materials sector typically signals durable demand rather than speculative surges, which means firms that invest early in manufacturing precision, engineering partnerships, and specification capture can compound advantages over multiple budget cycles.
Crucially, the macro path only becomes actionable when tied to segmentation behavior, pricing architecture, and competitive response patterns. That is where the full study adds differentiated value: it disaggregates the trajectory into the operational dimensions that determine which players capture share, which applications become margin leaders, and which geographies transition from emerging interest to sustained deployment.
Decoding the Market Architecture
The LGS market is not a single demand pool. It is a matrix of framing solutions, application requirements, and regional procurement cultures that reward different capabilities. Our research unpacks this matrix through three analytical lenses: type, application, and region. Rather than presenting these as isolated charts, the study evaluates how they interact to shape pricing power, specification risk, and distribution priorities.
Type-Level Dynamics
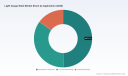
The framing category encompasses wall-bearing systems, skeleton framing, long-span solutions, and other specialized types. Each carries distinct engineering requirements, installation workflows, and end-user expectations. Wall-bearing systems tend to align with repetitive structural layouts and faster envelope completion. Skeleton framing supports flexible interior configurations and load distribution strategies. Long-span applications address larger clear-height requirements and specialized architectural programs. The report examines how these type segments differ in specification drivers, fabrication tolerances, and competitive positioning, helping manufacturers and distributors decide where to concentrate engineering resources and sales specialization.
Application Pathways
Residential construction, commercial buildings, and industrial buildings represent the principal application pathways. Their demand profiles diverge significantly in procurement cadence, volume consistency, and tolerance for design customization. Residential demand is shaped by housing velocity, build-system standardization, and regional labor availability. Commercial demand responds to tenant improvement cycles, office and hospitality renovation activity, and the push toward modular interiors. Industrial demand is influenced by warehouse expansion, logistics infrastructure, and light-manufacturing facility construction. The report maps how these application segments interact with framing type preferences and regional procurement habits, providing a basis for prioritization in product roadmaps and channel strategy.
Regional Realities
Regional markets operate under different code environments, sourcing expectations, and competitive densities. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each present distinct opportunities and constraints. The research avoids superficial regional comparisons and instead evaluates how local specification culture, trade dynamics, and adoption maturity influence market behavior. Decision-makers receive context on where distribution networks need strengthening, where engineering partnerships accelerate specification, and where local manufacturing or assembly capabilities create defensibility.
By weaving type, application, and region together, the study reveals where growth is most concentrated, where substitution risk is highest, and where strategic entry or expansion would yield the strongest return on effort. The complete segmentation analysis in the full report provides the quantified foundation for those decisions without exposing the underlying splits in advance, preserving the integrity of the intelligence for clients who need to benchmark against their own pipeline and capacity assumptions.
Competitive Landscape and Strategic Positioning
One of the strongest features of this research is its structured evaluation of the companies actively defining LGS market behavior. The competitive field spans established framing manufacturers, structural component suppliers, cold-formed steel specialists, and broader steel ecosystems that extend into LGS applications. Rather than treating these players as a simple roster, the study assesses them through the lens of capability depth, geographic reach, and strategic posture.
The market structure reflects meaningful concentration. The top three firms collectively account for approximately 55.0 percent of market share, while the top five reach around 65.0 percent. This concentration pattern signals that scale, specification relationships, and manufacturing consistency are becoming decisive advantages. At the same time, the presence of multiple regional specialists and product-focused innovators indicates that differentiation remains possible for firms that excel in installation precision, engineering support, or targeted application expertise.
The competitive analysis profiles a broad cross-section of organizations, including ClarkDietrich Building Systems LLC, WARE Industries, Inc., CEMCO, Hadley Industries PLC, Genesis Manazil Steel Framing, Scottsdale Construction Systems Ltd, Nucor Building Systems, Studco Building Systems, Tata BlueScope Steel, The Steel Network, Inc., ArcelorMittal S.A., Precision Walls Inc., FRAMECAD Limited, MiTek Industries, Inc., Stratus Steel, EPACK Prefab, MBA Building Supplies, Aegis Metal Framing, Radius Track Corporation, and Steel Frame Solutions Ltd.
Each profile is evaluated for its operating footprint, product system orientation, and relevance to specific application or regional contexts. For example, firms headquartered in the United States and United Kingdom often reflect mature framing ecosystems with strong specification channels, while entities operating in Australia, the Middle East, India, and New Zealand illustrate how LGS is gaining traction in markets seeking faster construction cycles, material consistency, or prefabricated system adoption. The study does not merely list these companies; it situates them within competitive clusters, assesses where they are likely to compete on price versus value, and identifies which organizational profiles are best positioned to benefit from the forecast trajectory.
This competitive layer is essential for 2026 strategy because the market is not expanding in a vacuum. Growth will be allocated according to who can execute on installation reliability, engineering support, supply continuity, and specification influence. The report provides the framework needed to determine whether your organization should compete through scale, specialization, regional depth, system integration, or partnership-led distribution.
Regulatory Signals and Industry Dynamics Reshaping Deployment
Materials markets do not move solely on demand; they move on the standards, certifications, and technical updates that govern specification and liability. In 2026, several developments are already reshaping how engineers, contractors, and manufacturers approach cold-formed steel and light gauge steel systems. The report integrates these dynamics into its forward-looking analysis so that strategic recommendations reflect not just market size but also the rules of engagement.
A notable technical milestone is the publication of CFSEI Tech Note J200-26 on the vibration of cold-formed steel joist framed floors. Updates of this nature matter because they influence floor system design assumptions, acoustic and serviceability considerations, and the confidence with which engineers specify LGS assemblies in multi-unit and commercial projects. When technical guidance evolves, specification behavior evolves with it, and manufacturers that align product documentation, engineering support, and training to the new expectations can strengthen their position in the specification pipeline.
Alongside the technical update, the CFSEI 2026 Expo in Long Beach, California brought together more than 250 engineers to discuss resilience and real-world solutions for cold-formed steel framing. Events of this scale are more than industry gatherings; they are indicators of where professional attention is concentrating, which performance themes are gaining prominence, and how knowledge transfer is shaping adoption. The research interprets these gatherings as signals of specification momentum and workforce readiness, both of which affect the speed at which LGS solutions move from consideration to repeatable deployment.
Innovation in installation precision is another dynamic shaping the market. The Steel Network's introduction of NotchTrak in April 2026 reflects an industry-wide emphasis on improving accuracy and efficiency in LGS framing installation. Products and systems that reduce field variability, shorten assembly time, or improve alignment can influence contractor preference and repeat procurement. The study evaluates how such launches alter competitive differentiation and what they imply for manufacturers seeking to compete on total installed value rather than component price alone.
Talent development is also part of the market's future readiness. CFSEI's announcement of 2026 Student Competition winners and stipend recipients highlights continued investment in the next generation of cold-formed steel design talent. For long-term market planning, this matters because specification ecosystems depend on engineers who understand LGS behavior, design constraints, and system integration. The report frames talent pipelines as an underappreciated but real driver of sustainable demand, especially in markets where engineering capacity can either accelerate or bottleneck adoption.
By embedding these regulatory and industry dynamics into the broader forecast, the research ensures that strategic recommendations are grounded in how the market actually changes, not just how it grows. The complete dynamic analysis in the full report connects these developments to regional specification environments, competitive responses, and application-level implications.
What Decision-Makers Can Expect Inside the Full Study
This market research is built for practical use. It is structured to support capital planning, product strategy, channel expansion, competitive benchmarking, and specification positioning. The full study translates the macro and competitive framework into a detailed operational reference that can be aligned with internal planning cycles.
Inside the report, readers will find:
- A comprehensive market sizing and forecast architecture that links historical performance to forward trajectory across the 2026 to 2032 window.
- Segmentation analysis that evaluates framing types, application pathways, and regional demand behavior in a manner designed for prioritization and resource allocation.
- Competitive profiles that place key companies in context, highlighting operating footprints, product system orientations, and strategic positioning.
- Market concentration analysis that clarifies where scale advantages matter and where differentiation remains viable.
- Industry dynamics coverage that ties technical standards, product launches, exhibition activity, and talent development to specification and deployment behavior.
- Strategic implications tailored for manufacturers, distributors, engineering-focused suppliers, and construction-system integrators seeking to act in 2026 and beyond.
The study does not stop at describing the market. It provides the analytical scaffolding needed to interpret where opportunity is most durable, where competitive pressure will intensify, and how to sequence investments for maximum impact. Detailed quantitative splits, company-level benchmarking, and region-specific deployment insights are presented in full within the report so that they can be used for internal modeling and board-level discussion with complete confidence.
How This Research Supports 2026 Strategy
In a market expanding from 44.71 billion USD in 2026 toward 63.02 billion USD by 2032, the strategic question is not simply how large the opportunity is, but how to capture the right portion of it with the right capabilities. The report is designed to help organizations answer that question with precision.
For manufacturers, the research clarifies where product development and fabrication investments are likely to generate the strongest returns, based on application demand and competitive positioning. For distributors and building-system suppliers, it highlights where regional coverage, specification support, and installation reliability can create durable advantage. For engineering-led organizations and component innovators, it identifies where technical updates and precision-focused product launches are reshaping preference and procurement. For investors and corporate strategists, it provides a structured view of concentration, growth dispersion, and competitive dynamics that can inform entry, expansion, or partnership decisions.
The deliberate emphasis on strategic context over raw data exposure reflects the reality that market intelligence is most valuable when it helps leaders decide, not just when it helps them observe. By integrating macro trajectory, segmentation logic, competitive structure, and regulatory momentum into one coherent framework, the study gives executives a way to stress-test assumptions, prioritize initiatives, and align 2026 actions with the market's longer-term architecture.
Conclusion: Turn Forecast Confidence into Executable Strategy
The Light Gauge Steel market is entering a phase where growth is supported by structural adoption, technical refinement, and competitive consolidation. That combination rewards organizations that act with informed discipline rather than broad speculation. PW Consulting's Light Gauge Steel Market research delivers the depth, structure, and strategic framing needed to make those decisions with confidence.
The full report contains the complete segmentation analysis, detailed company evaluations, concentration data interpretation, and regional deployment insights that turn high-level trajectory into operational direction. For teams preparing capital plans, product roadmaps, channel strategies, or competitive responses for 2026 and beyond, the study offers a rigorous intelligence base to guide execution.
Access the full Light Gauge Steel Market research to retrieve the complete data architecture, segmentation detail, and strategic recommendations designed for immediate decision use.
For detailed analysis of this topic, please visit the official page: Light Gauge Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Global Consumer Lighting Market Size, Share & Forecast Report, 2034
By Manisha Choudhary, 2026-09-07
The global consumer lighting market revenue demonstrates strong growth from 2020 through 2035. The shift towards LED and smart lighting technologies, along with urban development in Asia Pacific and sustainable initiatives in Europe and North America, are major growth drivers. Revenue is anticipated to nearly double over this period, illustrating rising penetration of advanced lighting solutions and the increasing value of smart, connected products across all major applications.
Read More - https://bussinessinsights.com/research-report/global-consumer-lighting
Residential applications make up the highest share in the consumer lighting market in 2025 as urbanization and renovation projects intensify globally. Commercial applications follow, particularly with the growth of energy-efficient lighting in offices and retail. Industrial and outdoor segments are steadily growing, reflecting increased investments in smart city infrastructure and energy-saving projects by governments and businesses.
Request Free Sample - https://bussinessinsights.com/request/consumers-goods/global-consumer-lighting
Frequently Asked Questions
Who are the key players in Global Consumer Lighting industry?
The top five players in the Global Consumer Lighting industry are Signify (Philips Lighting), Osram Licht AG, GE Lighting (Savant Systems), Acuity Brands, and Panasonic Corporation. These companies lead the market through innovation, global presence, advanced product offerings, and strategic mergers and acquisitions to capture larger market shares.
What is the Global Consumer Lighting growth?
The Global Consumer Lighting market has experienced robust growth, driven by rising energy-efficient lighting adoption. For instance, Signify reported a 9% sales increase in 2023 due to expanding smart lighting solutions and eco-friendly products, reflecting a positive industry outlook with sustainability as a key growth factor.
Which segment accounted for the largest Global Consumer Lighting share?
The residential segment accounted for the largest market share in Global Consumer Lighting. The demand for decorative, smart, and energy-efficient lighting in homes has surged, especially with remote working trends. Penetration of LED and smart connected lighting systems remains highest in residential applications, fueling ongoing dominance.
Thanks & Regards,
Manisha C
sales@bussinessinsights.com